
Fact-checked against official provider documentation: September 14, 2026
Stablecoin cards with yield connect everyday card spending to a balance that can earn interest or DeFi yield.
Some let USDT or USDC earn until the moment it is spent. Others convert your stablecoins into a different earning asset, such as mUSD. A third group lets you borrow against stablecoin collateral, allowing the collateral to keep earning while you spend borrowed funds.
The important question is therefore not simply, “Which card has the highest APY?” It is:
What asset earns the yield, where does that yield come from, and what happens to the asset when I pay?
This guide compares current stablecoin-card models and explains how to evaluate their real return after fees and risks.
For a broader comparison covering both crypto and stablecoin earning models, see our guide to crypto cards with yield.
Disclosure: Pionex publishes this guide and provides one of the products discussed. The comparison is based on official provider documentation and is not a ranking. Rates, fees, supported assets, and regional availability can change.
Contents
- 1 What Is a Stablecoin Card With Yield?
- 2 Can Stablecoins Earn Yield While Remaining Spendable?
- 3 Stablecoin Cards With Yield Compared
- 4 USDT, USDC, or mUSD: Which Earning Asset Does the Card Use?
- 5 How to Calculate Yield After Card Fees
- 6 What Risks Should You Check?
- 7 How to Choose a Stablecoin Yield Card
- 8 Frequently Asked Questions
- 9 Sources
What Is a Stablecoin Card With Yield?
A stablecoin card with yield is a payment card connected to a stablecoin balance or collateral position that can generate an annualized return.
The card itself does not create the return. The provider puts eligible funds to work through activities such as lending, market-neutral trading, or automated DeFi strategies. It then credits some form of interest, reward, or yield to the user.
Stablecoin cards usually follow one of three models:
| Model | What earns | What happens when you pay |
|---|---|---|
| Earning card balance | Stablecoins held in the card account | The purchase and applicable fees are deducted from that balance |
| Linked earning account | Stablecoins or a converted stable asset in a linked account | The card draws from the account when used |
| Yield-bearing collateral | Stablecoins supplied to a lending market or vault | The card creates a loan against the collateral, or directly spends an eligible balance |
These models can look similar in an advertisement but behave differently in practice.
With a direct-spending model, the amount used for the purchase stops earning because it leaves the account. With a collateralized model, the stablecoin can continue earning, but the user starts paying interest on a loan.
Can Stablecoins Earn Yield While Remaining Spendable?
Yes. Several providers let eligible stablecoin balances accrue yield while remaining available for card spending.
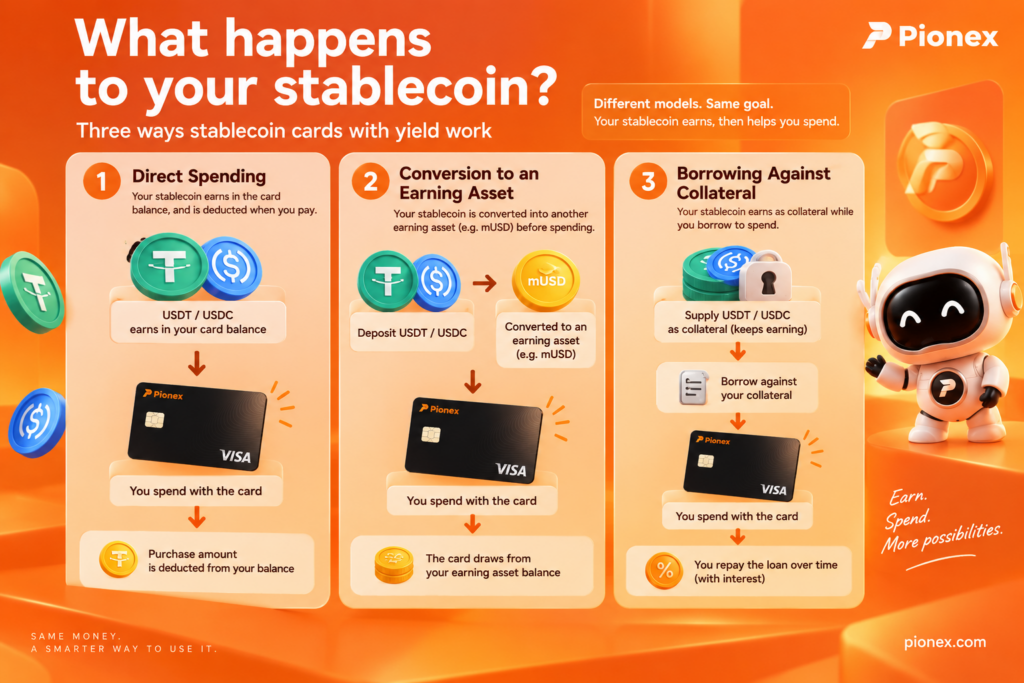
But “available to spend” can mean one of three things:
- The stablecoin stays in the card balance until payment. The used amount is deducted at checkout, while the remaining balance keeps earning.
- The stablecoin is converted into another earning asset. For example, deposited USDC might become mUSD before it starts earning.
- The stablecoin becomes collateral. It continues earning while the cardholder borrows against it, subject to interest and liquidation rules.
The balance does not keep earning after it has been spent. The useful feature is that the unspent portion can remain productive instead of sitting idle in a separate card wallet.
Stablecoin Cards With Yield Compared
The products below connect stablecoin earning and card spending in different ways. This is a selected comparison, not an exhaustive list.
| Product | Relevant stablecoin | How it earns | How the card spends | Published rate information | Custody model |
|---|---|---|---|---|---|
| Pionex Card | USDT | Eligible USDT in the Visa Card Account accrues Flexible Earn interest | Purchase amount and applicable fees are deducted from the card balance | 5% APY published for the Visa Card Account | Custodial |
| MetaMask Card with Money Account | mUSD; USDC and DAI can be converted into mUSD | mUSD is deployed through third-party DeFi platforms and accrues daily | The linked card spends mUSD from Money Account | Up to 4% standard APY; a limited offer advertises about 6% through September 30, 2026 | Self-custodial account within MetaMask |
| Nexo Card | Eligible stablecoins including USDT and USDC | Assets in the Savings Wallet can earn daily interest | Debit Mode uses the balance; Credit Mode borrows against collateral | Card guidance advertises up to 13% on eligible balances; the actual rate depends on asset, tier, settings, and jurisdiction | Custodial |
| ether.fi Cash | Current Direct Pay guidance lists USDC, USDT, EURC, LiquidUSD, LiquidReserve, LiquidEUR, and frxUSD | Borrow-eligible balances are supplied to an onchain lending market; Liquid vaults use automated DeFi strategies | Direct Pay spends eligible assets; Borrow Mode creates debt against collateral | Variable rates shown in the app; no single fixed card APY | Non-custodial smart-contract account |
Sources: Pionex Card review and source summary, MetaMask Money Account documentation, Nexo Card explainer, ether.fi Direct Pay asset guidance, and ether.fi lending documentation.
The comparison date matters. MetaMask’s higher advertised rate is explicitly temporary, while ether.fi’s rates change with market supply and demand. Pionex publishes a fixed headline rate for the eligible Visa Card Account, but the provider can revise its program terms.
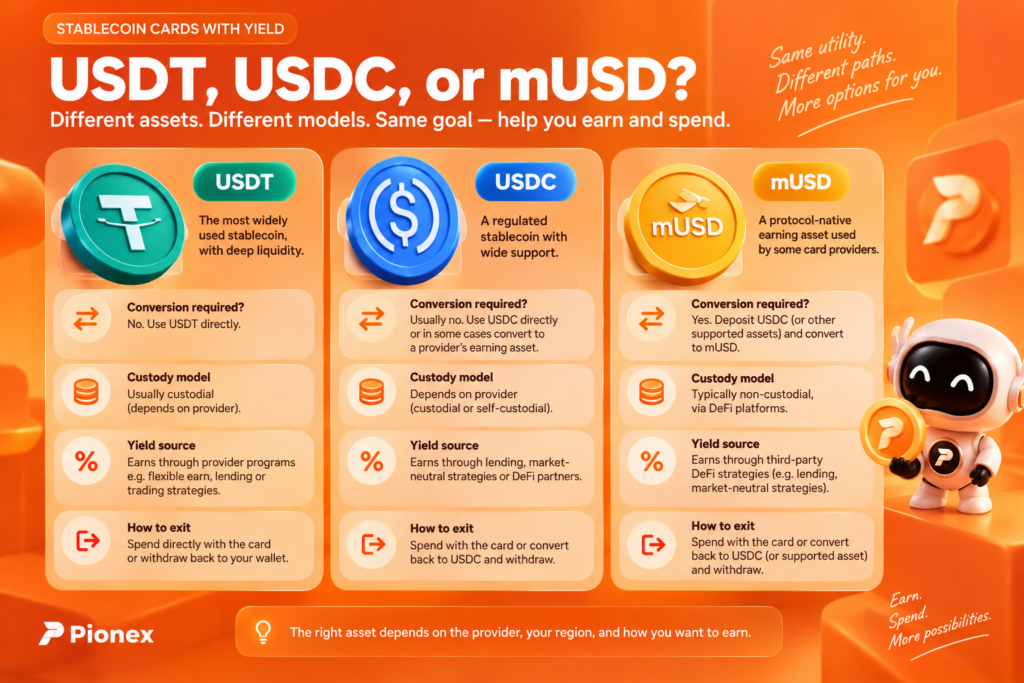
USDT, USDC, or mUSD: Which Earning Asset Does the Card Use?
Two cards can both be described as “stablecoin yield cards” while exposing users to different assets and systems.
USDT Cards
USDT cards are useful for people who already hold Tether and do not want to convert into another stablecoin before funding their card.
Pionex Card is a direct example. Users move USDT from their main Pionex account into a separate card balance. Its current Visa documentation states that the eligible card balance earns 5% APY, with interest credited hourly and funds remaining available to spend.
The standard flow is debit-based rather than collateralized credit. When the card is used, the purchase and applicable fee are deducted from the USDT balance.
Pionex currently publishes a 1% Visa transaction fee and up to 1% cashback on eligible Visa spending. Because those percentages can offset each other only when a purchase qualifies for the full cashback, users should calculate fees and rewards separately.
See how Pionex Card works for the account-to-card funding process.
ether.fi also lists USDT among the assets currently selectable for Direct Pay. In its Borrow system, supported stablecoin balances can earn variable lending rewards and act as collateral. That structure is more flexible but more complex than a straightforward card balance.
USDC Cards
USDC appears in several card systems, but it does not always remain USDC.
Nexo lets eligible USDC in a Savings Wallet earn according to the user’s product terms. In Debit Mode, the asset earns until it is used for a transaction. In Credit Mode, the user spends borrowed fiat backed by crypto assets.
ether.fi supports USDC for Direct Pay and as collateral. Its documentation says eligible assets supplied to its dedicated onchain lending market can earn a variable return. Collateral can continue earning while it backs a loan, but Borrow Mode adds interest and liquidation risk.
MetaMask accepts USDC as a funding asset for Money Account, but its documentation says supported deposits are converted into mUSD. The asset earning inside Money Account is therefore mUSD, not the original USDC.
mUSD and Yield-Bearing Stable Assets
mUSD is the stable asset used by MetaMask Money Account on the Monad network. MetaMask says it accrues yield daily, remains available to spend, and can be linked to MetaMask Card.
The standard advertised return is up to 4% APY. A limited promotion advertises approximately 6% through September 30, 2026. The APY is variable and not guaranteed.
MetaMask describes Money Account as self-custodial, but the product is tied to MetaMask and cannot be exported into another wallet as a separate account. Users can transfer assets out.
ether.fi’s LiquidUSD is another example of an asset connected to underlying yield strategies. Its Liquid product allocates deposits across DeFi strategies, rebalances them, and compounds rewards automatically. The displayed APY is a current blended rate, not a fixed return.
Before converting a familiar stablecoin into a protocol-specific asset, check:
- How the new asset maintains its target price
- Whether it can be redeemed directly
- Which blockchain it uses
- What fees apply when moving or swapping it
- Which smart contracts or third-party protocols generate the yield
- What happens if the provider interface is unavailable
How to Calculate Yield After Card Fees
APY and cashback describe different activities:
- APY is based mainly on the average eligible balance and time held.
- Cashback is based on qualifying spending.
- Card fees are based on spending, conversion, borrowing, or other actions.
A simple monthly estimate is:
Estimated net value = average balance × APY ÷ 12 + eligible cashback − card costs
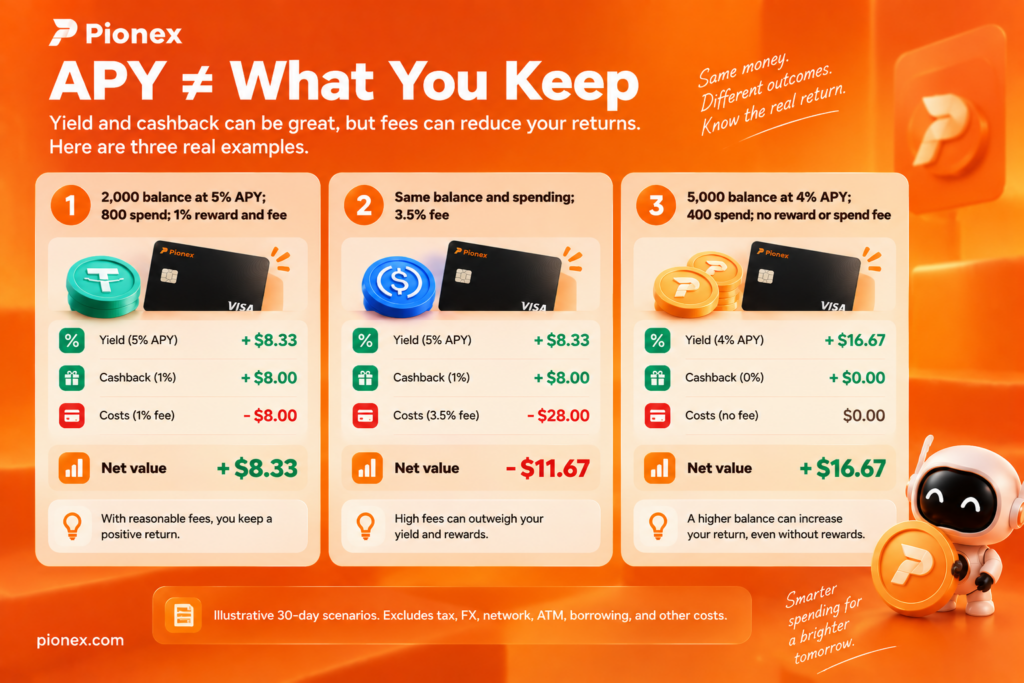
Suppose you keep an average balance of 2,000 stablecoins at 5% APY and spend 800 during a 30-day month.
- Approximate monthly yield: 2,000 × 5% ÷ 12 = 8.33
- Cashback at 1% on 800 of qualifying spending = 8.00
- Transaction fee at 1% on 800 = 8.00
- Approximate net value before other costs = 8.33
Now keep the same balance and spending but increase the transaction cost to 3.5%:
- Transaction cost = 28.00
- Approximate net value = 8.33 + 8.00 − 28.00 = −11.67
| Scenario | Approximate yield | Cashback | Card cost | Approximate net value |
|---|---|---|---|---|
| 2,000 average balance, 5% APY, 800 spend, 1% reward, 1% fee | 8.33 | 8.00 | −8.00 | 8.33 |
| Same balance and spend, but 3.5% fee | 8.33 | 8.00 | −28.00 | −11.67 |
| 5,000 average balance, 4% APY, 400 spend, no reward, no spend fee | 16.67 | 0.00 | 0.00 | 16.67 |
These examples are illustrations, not expected returns. They exclude changes in the balance, compounding differences, stablecoin price movement, foreign exchange, borrowing interest, ATM charges, network fees, taxes, and reward exclusions.
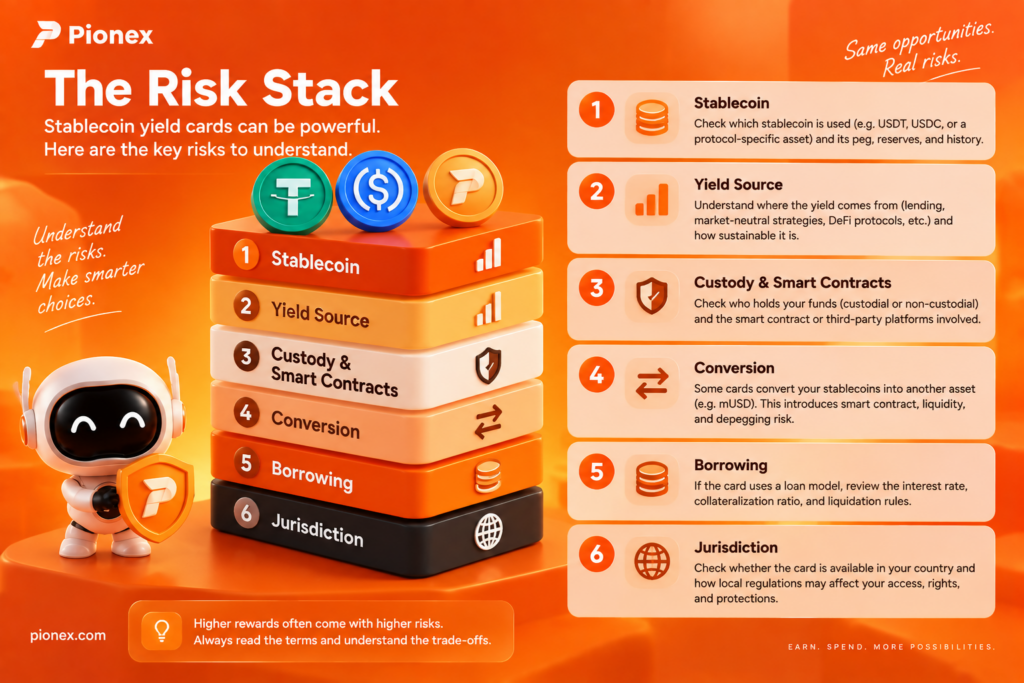
What Risks Should You Check?
Stablecoins reduce the day-to-day price volatility associated with assets such as Bitcoin or Ether. They do not remove financial risk.
Stablecoin Depeg Risk
A stablecoin can trade below its target value. A 5% annualized return would not compensate for a sudden loss of 10% in the asset’s market value.
Check the stablecoin issuer, reserve information, redemption process, trading liquidity, and the networks on which the token circulates.
Yield-Source Risk
Ask where the return originates.
Lending yield depends on borrower demand and repayment mechanisms. DeFi vaults introduce smart-contract and strategy risks. Market-neutral approaches can still face execution, counterparty, liquidity, and extreme-market risks.
If the provider does not explain the source of the yield, the headline rate alone is not enough information.
Custody and Smart-Contract Risk
With a custodial product, the provider controls the account infrastructure and may impose withdrawals, compliance reviews, or account restrictions.
With a self-custodial product, the user controls wallet credentials, but smart contracts, protocols, bridges, and wallet security become more important.
Neither model is automatically safer in every situation.
Conversion and Network Risk
A “USDC card” may convert USDC into another token before it earns. Moving that asset to a different network or back into USDC can create swap, bridge, network, slippage, or liquidity costs.
Read the deposit and withdrawal flow, not just the supported-assets list.
Borrowing and Liquidation Risk
Borrow Mode allows collateral to keep earning, but the user also pays a variable borrowing rate. If debt grows or collateral value falls, liquidation can occur.
ether.fi currently publishes a 90% maximum loan-to-value ratio and 95% liquidation threshold for USDC and USDT. Using the maximum borrowing capacity leaves little room for interest growth or price movement.
Its Cash Protection Program also states that it is not deposit insurance and does not cover stablecoin depegs, market losses, or yield shortfalls.
Regulatory, Tax, and Availability Risk
Card access depends on residence, identity verification, supported jurisdictions, and provider rules. Stablecoin spending or collateralized borrowing can also have tax consequences that vary by country.
Check the live application screen and obtain local tax advice where necessary.
How to Choose a Stablecoin Yield Card
Start with the stablecoin you already use, then work through the card’s complete money flow.
- Choose the asset. Decide whether you want to keep USDT or USDC, or are comfortable converting into mUSD or another yield-bearing asset.
- Confirm where the asset sits. Is it in a custodial card account, a savings wallet, or your own smart-contract account?
- Identify the yield source. Look for a clear explanation of lending, DeFi, market-neutral trading, or another source.
- Separate the normal rate from promotions. Record the standard APY, temporary rate, eligibility conditions, and end date.
- Check what happens when you pay. Does the card deduct the stablecoin, convert it, or borrow against it?
- Calculate net value with your numbers. Use your likely average balance and monthly spending rather than the provider’s maximum rate.
- Review every exit cost. Check card, FX, swap, bridge, network, withdrawal, ATM, membership, and borrowing costs.
- Examine failure risks. Include depeg, custody, smart-contract, protocol, liquidity, and liquidation risks.
- Verify eligibility before depositing. Confirm your country, KYC level, card network, and physical or virtual card availability.
For someone who already holds USDT and wants a direct earning card balance, a USDT-funded debit structure may be easier to understand. Someone who prioritizes self-custody may prefer a linked DeFi account. Someone who wants to avoid selling may consider collateralized spending, but only after assessing its loan costs and liquidation rules.
The suitable choice depends on the complete structure—not one APY number.
Frequently Asked Questions
Which stablecoin cards pay interest?
Current documented examples include Pionex Card for an eligible USDT Visa Card Account, MetaMask Card linked to an mUSD Money Account, eligible Nexo Savings Wallet balances used with Nexo Card, and borrow-eligible stablecoins connected to ether.fi Cash. Their rates, custody models, and spending methods differ.
Can I earn USDC yield and still spend it?
Yes, but the implementation varies. Nexo can let eligible USDC earn until it is used in Debit Mode. ether.fi can supply eligible USDC to a lending market and support Direct Pay or collateralized spending. MetaMask accepts USDC as a funding asset but converts it into mUSD inside Money Account.
Can I earn USDT yield and spend it with a card?
Pionex’s eligible Visa Card Account is a direct example: USDT in the separate card balance earns until it is spent. Other platforms may support USDT as a savings balance, Direct Pay asset, or collateral.
Is a stablecoin yield card the same as a savings account?
No. Stablecoin accounts are not automatically bank accounts or insured deposits. They can involve crypto custody, smart contracts, lending protocols, stablecoin depegs, and changing rates.
Is APY better than cashback?
Neither is always better. APY favors a larger average balance held for longer. Cashback favors qualifying spending. Compare the expected value of both and subtract all fees.
Does a stablecoin keep earning after I spend it?
No. The portion that has been spent no longer earns for you. The remaining eligible balance may continue earning. In a borrowing model, the collateral may continue earning, but the new loan accrues interest.
Sources
We reviewed official product and support documentation available on September 14, 2026. This is a documentation-based comparison, not a hands-on card test. Live account terms should take precedence if they differ from a public article.
Primary sources:
- Pionex Card Review: Fees, Cashback and Limits
- How Does Pionex Card Work?
- Pionex Card Fee Structure Update
- MetaMask Money Account
- Nexo Card: Spend Without Giving Up Your Crypto
- ether.fi: Change Direct Pay Spend Priority
- ether.fi: How Borrow Works
- ether.fi: Lending and Collateral
- ether.fi: Collateral and Borrowing
- ether.fi Cash Protection Program
